Rwanda Tightens Corporate Governance Rules for Capital Market Companies
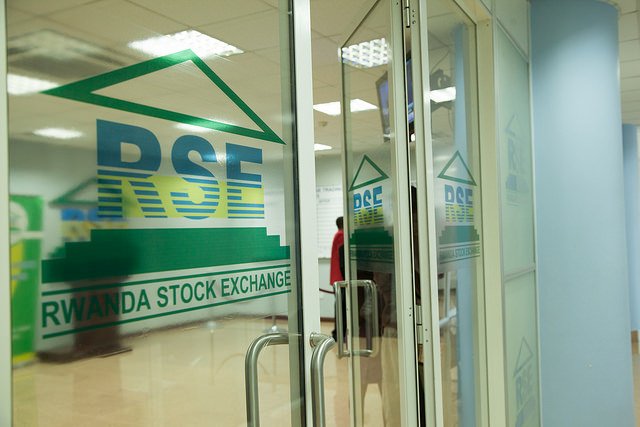
New regulations put greater emphasis on board independence, transparency, shareholder rights, risk management and environmental and social responsibility
KIGALI, RWANDA — Rwanda has introduced a new corporate governance framework for companies operating in, or seeking to access, the country’s capital market, with the rules placing stronger emphasis on board independence, accountability, transparency, investor protection and environmental and social responsibility.
The Capital Market Authority (CMA) issued Regulations No. 002/CMA/2026 relating to Capital Market Corporate Governance, published in the Official Gazette on 2 October 2026. The regulations replace the earlier 2012 corporate governance code and come into force on the date of publication.
The new framework applies not only to listed companies and issuers of securities to the public, but also to companies intending to issue securities to the public, public and State-owned companies, private companies and small and medium enterprises.
For investors and companies, the changes signal a broader expectation that corporate governance should extend beyond boardroom procedures to encompass how companies manage risk, treat shareholders and stakeholders, disclose information and address environmental and social issues.
Boardrooms face stronger independence requirements
One of the most significant provisions concerns the composition and independence of boards.
Under Article 6, a company’s board should generally have between seven and 11 directors, depending on the size, nature and complexity of its operations. Small and medium enterprises are required to have between three and five directors.
At least half of the board must be non-executive directors, with additional requirements concerning independent directors. Independent directors are compensated through sitting allowances.
The regulations also draw a clear line between the roles of the board chairperson and chief executive.
Under Article 17, the Chief Executive Officer cannot simultaneously serve as Chairperson of the Board. The Chairperson must meet the criteria for an independent director, while the division of responsibilities between the two positions must be formally documented in the board charter.
The principle is straightforward: concentrating too much authority in one individual can weaken accountability.
By requiring separation between the board’s leadership and executive management, the regulations seek to strengthen checks and balances within companies.
Audit and risk management move to the centre
The new framework also places significant weight on risk management and internal controls.
Companies are expected to identify, assess and prioritize material risks continuously and establish effective responses to those risks. Larger companies and those with more complex business models are encouraged to consider establishing a separate committee dedicated to risk oversight.
The regulations also strengthen the role of audit committees.
An Audit Committee must have at least three directors, with the majority being independent directors. Its chairperson must be an independent director and a financial expert with relevant qualifications and experience in auditing, finance or accounting, and must belong to a professional body in good standing.
For listed companies, the regulations require a properly resourced and competent internal audit function capable of providing the board with independent and objective assurance on operations, risk management, controls and governance. The internal audit function must be independent from management and operate under an Internal Audit Charter.
Minority and foreign shareholders get clearer protections
The regulations also address the relationship between companies and their shareholders.
Companies must ensure equitable treatment of shareholders, including minority and foreign shareholders. Shareholders within the same class must have equal rights concerning voting, subscription and transfer of shares, while companies must have clear and published policies concerning minority shareholder rights.
The regulations further establish the principle of “one share, one vote” for voting rights, while requiring companies to make information on voting rights available to current and potential shareholders.
Proxy voting procedures are expected to be simple and accessible, with the relevant information provided alongside notices and materials for annual general meetings.
For investors, these provisions could make corporate decision-making more transparent and participation in shareholder meetings easier to understand.
Companies will have to listen beyond their shareholders
Perhaps one of the more consequential shifts is the formal recognition of wider stakeholders.
The regulations require companies to establish formal stakeholder engagement policies and processes that identify key stakeholders, consider their material needs, interests and expectations, and report on engagement activities.
The framework also links corporate responsibility to employee and customer health, safety, dignity and well-being, as well as measures to prevent, detect and respond to fraud and corruption.
Companies are also expected to mitigate the negative effects of their operations on the environment and communities where they operate.
That gives environmental, social and governance (ESG) considerations a clearer place within the corporate governance framework. The regulations explicitly define ESG as environmental, social and governance matters considered by companies.
For companies seeking investment, the implication is increasingly clear: governance is no longer only about financial performance. How a company manages its social and environmental footprint can also form part of the information available to stakeholders.
A stronger voice for whistleblowers
The regulations also require companies to establish mechanisms through which employees, suppliers, customers, affected communities and other stakeholders can confidentially raise concerns about suspected or actual non-compliance, fraud or misconduct.
Companies must communicate these mechanisms in a format and language that stakeholders can understand, while protecting people who report concerns in good faith from negative repercussions.
This provision could be particularly important in strengthening internal accountability and giving stakeholders a channel to raise concerns before problems escalate.
Annual reports become a more important accountability tool
Transparency is another major pillar of the new framework.
Companies are expected to provide stakeholders with timely and accurate information on material matters, including their financial and non-financial position, strategy and risk management, business model, performance, ownership, and environmental and social matters.
The regulations require companies to publish comprehensive, understandable and balanced annual reports and to use their websites regularly for timely disclosure.
Company websites should provide updated information including annual reports, interim reports, investor briefings, company policies, board charters and board committee charters.
The rules go further by requiring material information relevant to the value of shares or investors to be published immediately. Annual reports must also identify major shareholders, including beneficial shareholders, and provide a balanced presentation of relevant financial and non-financial information.
ESG and sustainability enter formal reporting
The new rules give sustainability and non-financial reporting a more prominent role.
Article 47 addresses disclosure relating to sustainability, non-financial information, stakeholder engagement and corporate social and environmental responsibilities in annual reports.
The regulations also require disclosure around executive and board remuneration. The remuneration committee is expected to disclose the company’s remuneration policy, levels and structure, as well as the process used to determine remuneration for directors and management, allowing investors to understand the relationship between remuneration and performance.
Meanwhile, each director’s commitment to ethical and effective leadership and good governance is to be confirmed by the board in a statement included in the annual report.
What this means for Rwanda’s capital market
The new regulations come at a time when Rwanda is seeking to deepen its capital market and expand access to investment.
Their significance goes beyond compliance checklists.
For companies, the new framework means that board structure, internal controls, risk management, shareholder treatment, stakeholder engagement, sustainability and public disclosure are increasingly interconnected.
For investors, stronger governance can provide more information with which to assess companies and their risks.
For boards, the rules raise expectations around independence, competence, oversight and accountability.
And for the wider public, greater disclosure could make it easier to understand how companies affect employees, communities, consumers and the environment.
The regulations make clear that a well-governed company is expected to be accountable not only to its shareholders, but also to stakeholders, creditors and employees.
The bigger question: can governance strengthen investor confidence?
The publication of the regulations marks an important step in formalizing corporate governance expectations within Rwanda’s capital market.
But the real test will come through implementation.
Companies will need to translate the new requirements into functioning boards, effective committees, credible internal controls, meaningful stakeholder engagement and timely public disclosure.
Investors, meanwhile, will be watching whether these standards produce something beyond compliance documents: greater transparency, stronger accountability and increased confidence in Rwanda’s capital market.
For a market seeking deeper participation and long-term investment, that may ultimately be the most important measure of all.
Source: Official Gazette No. Special of 2 October 2026, Regulations No. 002/CMA/2026 relating to Capital Market Corporate Governance.
TOP AFRICA NEWS — Amplifying Development Impacts Across Africa.
About The Author

SUBSCRIBE TO OUR NEWSLETTER